Can Dispensaries Use Banks? Yes, But It's Complicated
Yes, licensed cannabis dispensaries like Garden of Eden can use banks, but options are limited. Most traditional banks avoid cannabis due to federal illegality, but state-chartered banks and credit unions often serve the industry. Cash management and compliance with reporting rules are key.
Which banks and credit unions actually serve dispensaries?
Finding a bank that works with cannabis businesses takes research. Most national banks avoid the industry, but state-chartered banks and credit unions often step in. Here's a comparison of common options:
| Institution Type | Examples | Key Features | Considerations |
|---|---|---|---|
| State-chartered banks | Herring Bank (Texas), Partners Bank (California) | Offer checking, savings, and merchant services; comply with FinCEN guidance | May require detailed compliance paperwork; fees can be higher |
| Credit unions | Local credit unions in CA (e.g., First Entertainment, Safe CU) | Often more willing to serve cannabis; lower fees; community-focused | Membership may be limited to certain regions or groups |
| Specialized cannabis banks | Fourth Corner Credit Union (Colorado), Dama Financial | Tailored services: cash management, pay-by-bank, tax payments | Higher monthly fees; may require minimum balances |
| National banks | Wells Fargo, Chase, Bank of America | Generally avoid cannabis due to federal risk | Most will not open accounts for marijuana-related businesses |
When choosing, look for institutions that file Suspicious Activity Reports (SARs) as needed and understand the Bank Secrecy Act (BSA) requirements. Ask about cash deposit limits and whether they offer pay-by-bank for customer transactions.
Can dispensaries use banks? Yes, but it's complicated
Yes, licensed cannabis dispensaries can use banks, but the relationship is complex due to federal law. While cannabis is legal in California and many other states, it remains a Schedule I substance under federal law. This means banks chartered at the federal level—like most large national banks—are hesitant to serve the industry, fearing federal penalties or asset seizure.
However, state-chartered banks and credit unions can and do work with dispensaries. They follow guidance from the Financial Crimes Enforcement Network (FinCEN), which allows them to serve marijuana-related businesses if they file appropriate reports and comply with the Bank Secrecy Act (BSA). As a result, many dispensaries, including Garden of Eden in Hayward, maintain bank accounts for deposits, payroll, and tax payments.
The key is finding a financial institution that understands the cannabis industry and has a compliance framework in place. It's not as simple as walking into any bank, but it is possible.
Why most banks won't work with cannabis dispensaries
Most traditional banks avoid cannabis businesses because of a fundamental conflict: cannabis is illegal under federal law, even where state-licensed. The DEA classifies marijuana as a Schedule I drug, which means any bank that handles cannabis money could be charged with money laundering or aiding a federal crime.
Banks also face strict reporting requirements under the Bank Secrecy Act (BSA). They must file Currency Transaction Reports (CTRs) for cash deposits over $10,000 and Suspicious Activity Reports (SARs) for any unusual transactions. The paperwork and legal risk often outweigh the potential profit for large national banks.
Additionally, the Federal Reserve and other federal regulators have not provided clear protection for banks serving the cannabis industry. Until laws like the SAFE Banking Act pass, many institutions will remain on the sidelines. That's why state-chartered banks and credit unions—which are regulated at the state level—are the most common choice for dispensaries.
Cash deposit rules: what dispensaries need to know
Dispensaries often deal in cash, and depositing it requires following federal rules. Here's what triggers reporting and what to expect:
| Deposit Amount | Rule | What Happens |
|---|---|---|
| Under $10,000 | No automatic report, but banks may still file a SAR if suspicious | Routine deposit; no IRS notification unless flagged |
| $10,000 or more | Currency Transaction Report (CTR) filed by bank | IRS receives the report; not illegal, but must be documented |
| Multiple deposits under $10,000 (structuring) | Illegal if done to avoid CTR | Can lead to criminal charges; banks will detect patterns |
| $3,000 or more (in cash from a single transaction) | May trigger a SAR if unusual | Bank files a Suspicious Activity Report; not automatic but common |
Key takeaway: Always deposit cash honestly. Breaking up deposits to stay under $10,000 is illegal structuring. Dispensaries should keep detailed records of all cash transactions and work with a bank that understands cannabis compliance.
Directions to our dispensary near me in Hayward from Ricky's Sports Theatre and Grill
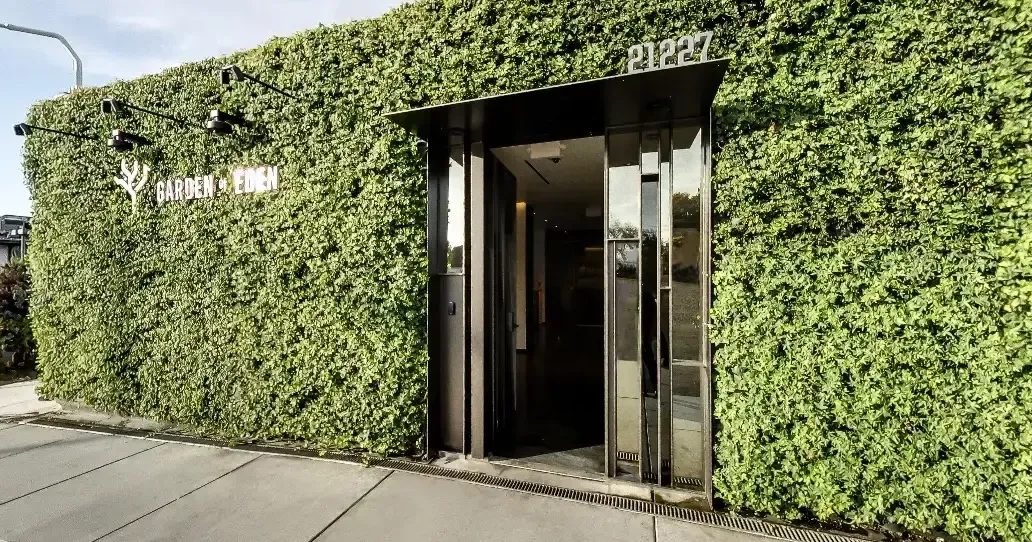
Start at Ricky's Sports Theatre and Grill and head to Garden of Eden at 21227 Foothill Blvd, Hayward, CA 94541.
How dispensaries handle banking, cash, and pay-by-bank
Running a dispensary means managing cash carefully. Here's how most operations handle it day-to-day:
- Open a cannabis-friendly bank account — Research state-chartered banks or credit unions that serve marijuana businesses. Provide your California license (e.g., C10-0000295-LIC) and compliance documents.
- Deposit cash regularly — Make daily or weekly deposits to avoid large cash accumulations. Keep receipts and logs for every deposit.
- Use pay-by-bank for customer transactions — Many dispensaries offer pay-by-bank (ACH) so customers can pay directly from their checking account, reducing cash on hand. This works like an electronic check.
- Pay employees via direct deposit — Once you have a bank account, set up payroll through a service that handles cannabis businesses. Employees receive their pay electronically.
- Pay taxes electronically — Use your bank account to pay federal and state taxes via EFTPS (federal) or California's tax portal. Keep records of all payments.
At Garden of Eden in Hayward, we follow these steps to keep our operations smooth and compliant. If you're a dispensary owner, start by contacting a credit union or state-chartered bank in your area.
The SAFE Banking Act and the future of cannabis banking
The SAFE Banking Act (Secure and Fair Enforcement Banking Act) is a federal bill that would protect banks serving state-licensed cannabis businesses from federal prosecution. If passed, it would allow more banks to work with dispensaries without fear of penalties, reducing the industry's reliance on cash.
As of 2025, the bill has passed the House multiple times but stalled in the Senate. The SAFER Banking Act (a revised version) is also under consideration. While the future is uncertain, the trend is toward greater banking access. For now, dispensaries must work with state-chartered institutions and comply with existing rules.
How dispensaries pay taxes and employees without traditional banks
Even without a traditional bank, dispensaries can manage taxes and payroll. Here's how:
- Pay federal taxes — Use the Electronic Federal Tax Payment System (EFTPS) with a bank account or pay via cash at a local IRS office (with a receipt).
- Pay state taxes — California allows electronic payments through the California Department of Tax and Fee Administration (CDTFA).
- Pay employees — Use a payroll service that specializes in cannabis (e.g., Gusto, ADP) and issue direct deposits or paper checks from your cannabis-friendly bank account.
At Garden of Eden, we handle all tax and payroll obligations through our bank account, ensuring compliance with both state and federal rules.
Banking options for California dispensaries
California dispensaries have several banking options. Here's how to get started:
- Contact a state-chartered bank or credit union — Look for institutions that openly serve cannabis businesses. Examples include Partners Bank and local credit unions in the East Bay.
- Prepare your documents — Have your California cannabis license, business tax ID, ownership details, and compliance plan ready.
- Ask about services — Inquire about checking accounts, cash deposit limits, pay-by-bank, and merchant services.
- Visit or call — Many institutions require an in-person meeting. If you're in Hayward, stop by Garden of Eden at 21227 Foothill Blvd and ask our team for recommendations—we've been operating since 2003 and know the local landscape.
For more details on how we handle banking, visit our dispensary near me Hayward page.
Sources
Also asked as
- How do dispensaries deposit money?
- Which banks work with cannabis businesses?
- Can marijuana dispensaries have bank accounts?
Frequently asked questions
Why can't dispensaries use banks?
Dispensaries can use banks, but many traditional banks avoid them because cannabis is federally illegal. The DEA classifies marijuana as a Schedule I drug, which creates legal risk for banks. State-chartered banks and credit unions often serve the industry instead.
Can I use my bank card at a dispensary?
Many dispensaries, including Garden of Eden, accept debit cards through pay-by-bank or ATM-style transactions. Credit cards are less common due to federal restrictions. Check with your local dispensary for payment options.
What is the $3,000 bank rule?
The $3,000 rule refers to a common threshold for Suspicious Activity Reports (SARs). Banks may file a SAR for cash transactions over $3,000 if they appear suspicious, but it's not a legal limit—it's a guideline for reporting unusual activity.
Is it illegal to have $10,000 cash on you?
No, it's not illegal to carry $10,000 in cash. However, if you deposit $10,000 or more in a bank, the bank must file a Currency Transaction Report (CTR) with the IRS. Structuring deposits to avoid this report is illegal.
How do dispensaries pay their employees?
Dispensaries pay employees through direct deposit or paper checks from a cannabis-friendly bank account. Many use payroll services like Gusto or ADP that specialize in cannabis businesses.